Back up, Less Crowded?
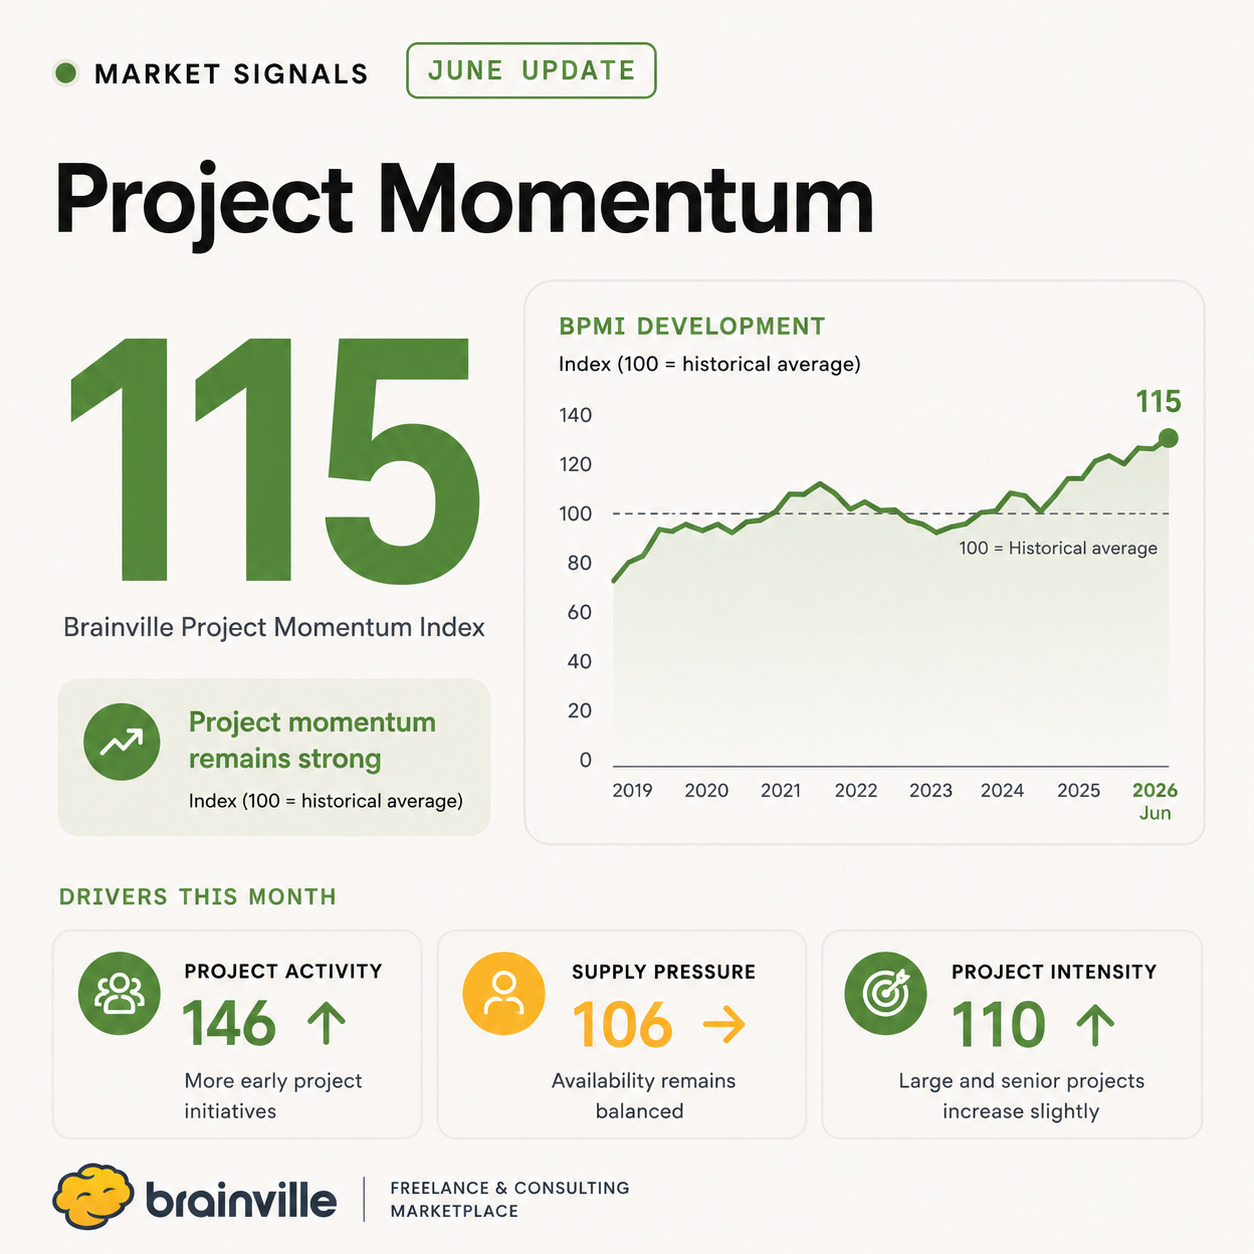
After a weaker April, the Nordic consulting market moved somewhat back up in May. At the same time, competition appears to have eased slightly – even if levels still seem relatively high.
📊 Assignments & competition
Assignment volume increased by +2.1% compared with April (excluding healthcare) and is +3.2% higher than May 2025. After April’s decline, the market moved in a more positive direction again in May, while still showing noticeable month-to-month variation rather than a clear upward trend.
The number of available consultants continued to decline (−9.7% compared with April and −12.8% year-on-year). Historically, we often see some seasonal softening heading into summer, although movements for consultants are usually smaller than for assignment volumes.
Applications per assignment declined by −12.8% compared with April. That may point to somewhat lower competition than earlier in spring, even if levels still appear relatively high.
Registrations on Brainville remain near all-time highs, suggesting continued strong activity in the market.
🌍 Geography
Metropolitan regions continued to develop slightly stronger than the market overall (+1.5% in May), although geographic differences remain relatively small.
🏠 Remote & hybrid work
The share of remote and hybrid assignments remained at a high level and increased slightly compared with April (+0.7%). Hybrid work continues to dominate clearly.
👩💻 Roles (Nordic perspective)
Increasing:
• Test roles (+1%)
• System Integration (+1%)
Declining:
• Data/BI (−1.5%) – perhaps somewhat surprising given the area’s strong development in recent years, even if these remain relatively small movements
• Business Analysis (−1%)
• SAP Consultant (−1%)
📸 Photo
On a run home from the city after a meeting. The best route is, of course, along the water or through the forest – here near Svindersvik Manor in Nacka.